
When people think about credit report repair, they often focus immediately on their credit score. But your score is only part of the picture. The information contained in your credit report can play an important role when you apply for credit, and understanding that information before you submit an application can help you make more informed financial decisions.
Whether you are thinking about a home loan, personal loan, car finance, credit card or another form of credit, one of the simplest things you can do is check your credit report first.
As Victoria from Credit Fix Solutions often says: knowledge is power.
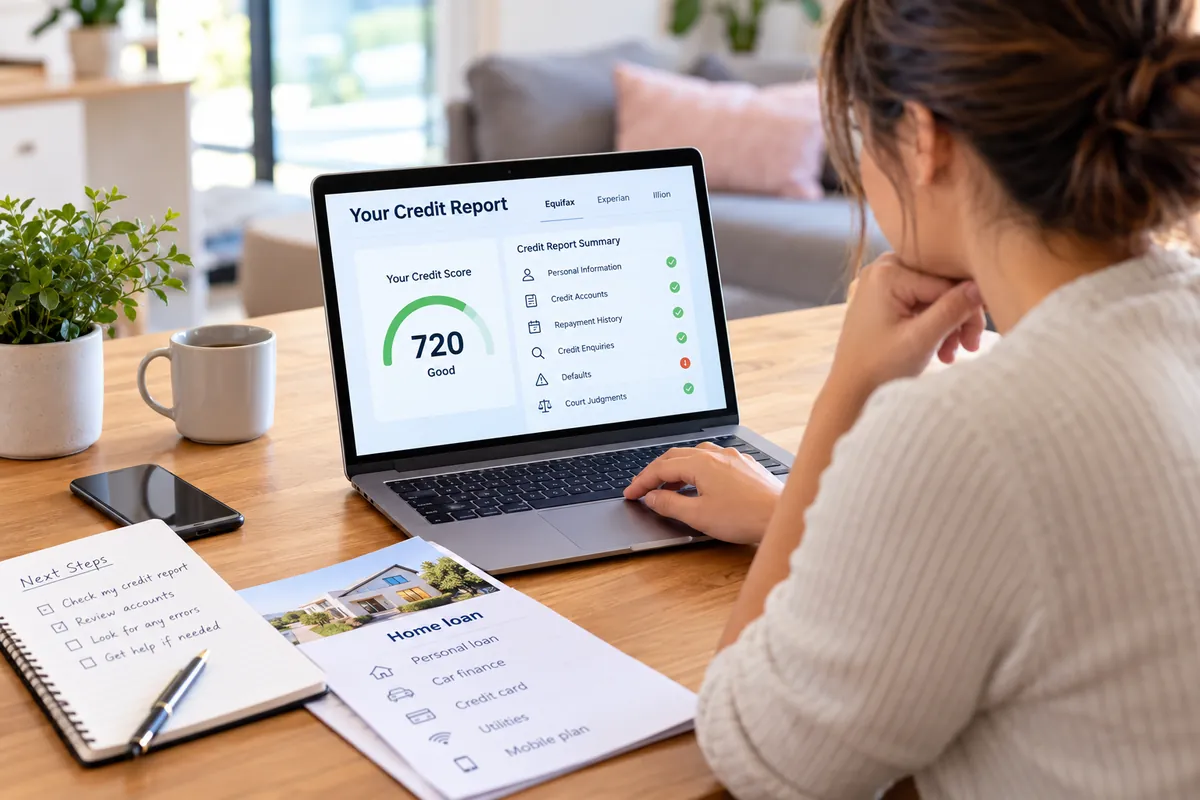
Your Credit Report Is More Than a Number
It can be easy to become focused on whether your credit score is “good” or “bad”. However, your credit score is calculated using information contained in your credit report, and lenders may consider information from your credit report when assessing an application.
Your report can contain information about the credit products you have held, your repayment history, credit enquiries and certain negative information such as defaults, court judgments or insolvency information.
This is why effective credit report repair starts with understanding the data rather than simply focusing on a number.
Before applying for finance, take the time to read your report carefully. Ask yourself: Do I recognise the accounts? Are my personal details correct? Do I recognise the credit enquiries? Is the repayment information accurate? Is there a default or other listing that I wasn’t expecting to see?
Finding a surprise after you have already applied for finance is very different from finding it beforehand.
You Can Check Your Credit Report for Free
In Australia, you have the right to access your consumer credit report for free every three months. Different credit reporting bodies can hold different information, so it can be worthwhile checking your reports rather than assuming the information will necessarily be identical.
Importantly, requesting your own credit report is not the same as applying for credit. Checking your own report allows you to understand the information recorded about you without creating a credit application enquiry.
The Australian Government’s Moneysmart website provides useful independent information about credit reports, credit scores and how to access your report for free.
What Should You Look for on Your Credit Report?
Don’t just download your report and look at the score at the top. Take some time to go through the information.
Check that your personal information is accurate and that the loans and credit accounts listed actually belong to you. Review your repayment history and credit enquiries, and pay attention to any negative information recorded on the file.
If you find information that appears incorrect, outdated or unfamiliar, don’t ignore it.
Australian credit reporting rules require credit reporting information to be accurate, up to date and complete. If information is incorrect, you can request that it be investigated and corrected.
However, it is important to understand that credit report repair does not mean that every negative listing can simply be deleted. Correctly reported and legitimate information generally cannot be removed just because it is affecting your creditworthiness.
How to Get a Default Removed From Credit File
One of the questions we regularly hear is: how to get a default removed from credit file?
The answer depends entirely on the circumstances surrounding the default.
A default appearing on your credit report does not automatically mean it can be removed. The first step is to understand what the listing relates to and whether the information has been reported correctly.
If you believe a default is inaccurate, does not belong to you, has been incorrectly reported or there may be another legitimate basis for challenging it, the matter can be investigated.
You may be able to contact the relevant credit provider or credit reporting body yourself and request a correction. In fact, where an issue is straightforward and can reasonably be handled directly, doing it yourself may be the most appropriate option.
For more complicated circumstances, professional assistance may help you understand the information on your report, the relevant credit reporting requirements and whether there are legitimate grounds for a dispute.
So, if you are searching how to get a default removed from credit file, be cautious of anyone promising that every default can be removed. Each case needs to be considered individually, and there are no guaranteed outcomes.
Why Check Before Applying for Finance?
Every time you are preparing for an important financial application, knowing what is on your credit report gives you an opportunity to identify potential problems beforehand.
Imagine preparing for a home loan application only to discover that there is an enquiry you don’t recognise, incorrect repayment information or a default you were unaware of. Discovering the issue early gives you time to understand what happened and determine whether anything needs to be investigated before you move forward.
It can also help you avoid making repeated applications simply because you don’t understand why an earlier application was unsuccessful.
Your credit report should therefore be something you understand and review periodically – not something you only think about after a finance application has been declined.
What If You Find Something Unexpected?
Don’t panic simply because you find something you weren’t expecting.
Start by understanding exactly what has been recorded, who reported it and whether the information appears accurate. Keep relevant documentation and correspondence, particularly if you believe there has been an error.
For straightforward errors, you can approach the relevant credit provider or credit reporting body yourself. Corrections to inaccurate credit reporting information can be requested without paying a credit repair company.
If you’re unsure what the information means or believe your situation is more complicated, you can seek further information or assistance.
At Credit Fix Solutions, we assess individual circumstances to determine whether there may be legitimate grounds to challenge an incorrect, inaccurate, unfair or potentially non-compliant listing. Where something can reasonably be handled yourself, we can also point you in the right direction.
Knowledge Comes Before Credit Report Repair
The most useful habit you can develop is simple: know what’s on your credit report before you need to use it.
Don’t wait until you’re sitting with a mortgage broker, applying for car finance or trying to organise another credit product to discover what your credit file contains.
Get your reports, read them carefully, understand the information and investigate anything that doesn’t look right.
A credit score may give you a quick snapshot, but the information behind that score tells a much bigger story.
If you’ve checked your credit report and found something that concerns you, contact Credit Fix Solutions today for a free assessment of your circumstances.
For independent information about credit scores, credit reports and your rights, visit the Australian Government’s Moneysmart website.
General information only: This article is intended for general educational and informational purposes and does not constitute financial, credit or legal advice. Credit reporting circumstances vary between individuals. Not all negative information can be removed, and Credit Fix Solutions does not guarantee eligibility, removal outcomes, credit score improvements, timeframes or finance approval.